TL;DR
Marriage connects many financial decisions, but couples often discuss wedding budgets before discussing savings, debts and long-term goals. Calculating combined net worth gives both partners a clear starting point. It does not require every account to become joint. It simply creates honesty about what each person owns, owes and hopes to build together.
Getting Married? Here’s How to Calculate Your Combined Net Worth
The Money Conversation Most Couples Skip
Planning a wedding makes money impossible to ignore. Venues, catering, outfits, travel and deposits all demand decisions. Yet the more important financial conversation often gets postponed: what does each partner own, what does each partner owe and what will the shared plan look like after the wedding?
Avoiding that discussion can create stress later. The American Institute of CPAs states that money is one of the top reasons couples argue, commonly around spending priorities, unplanned purchases and debt payoff. Yale School of Management has also reported research finding that people under financial stress are less willing to discuss money with a romantic partner because they expect conflict.
A combined net worth conversation is not about judging the person you love. It is about removing surprises. A student loan balance, a strong retirement account, credit card debt, business ownership or family financial obligation can all affect shared decisions such as housing, travel, children and retirement.
The conversation is easier when it begins with numbers rather than assumptions.
How to Calculate Your Combined Net Worth
Combined net worth follows the same formula used for one person:
Combined Net Worth = Both Partners’ Total Assets − Both Partners’ Total Liabilities
This calculation does not automatically turn separate property into jointly owned property. It creates a shared snapshot for planning purposes.
Step 1: Each Partner Lists All Assets
Begin separately. Each person should write down current values for accounts and assets they own, including:
- Checking and savings accounts
- Retirement accounts, such as 401(k), IRA or pension balances that can reasonably be valued
- Brokerage accounts and other investments
- Current home or property value, when applicable
- Vehicle resale value
- Business equity or other meaningful assets
Use current balances, not estimates based on memory. For a vehicle, use realistic resale value rather than the original purchase price. For a home, record current estimated value and list the mortgage separately as debt.
Step 2: Each Partner Lists All Liabilities
Next, record every amount currently owed:
- Student loans
- Auto loans
- Credit card balances
- Personal loans
- Mortgage or home equity loan balances
- Medical debt, tax debt or buy-now-pay-later balances
- Business debt personally guaranteed by either partner
Do not leave out a debt because it was created before the relationship or because one partner plans to pay it separately. A complete financial conversation requires seeing the full position first. Decisions about responsibility can come afterward.
Step 3: Combine the Numbers Into One Starting Balance Sheet
Suppose Partner A has $95,000 in assets and $28,000 in debts, giving them an individual net worth of $67,000. Partner B has $54,000 in assets and $72,000 in debts, giving them an individual net worth of negative $18,000.
Together, their planning snapshot is:
| Combined Position | Amount |
| Total assets | $149,000 |
| Total liabilities | -$100,000 |
| Combined net worth | $49,000 |
That number does not say one partner is financially “better” than the other. It tells the couple where they are beginning and what their first shared priorities might be.
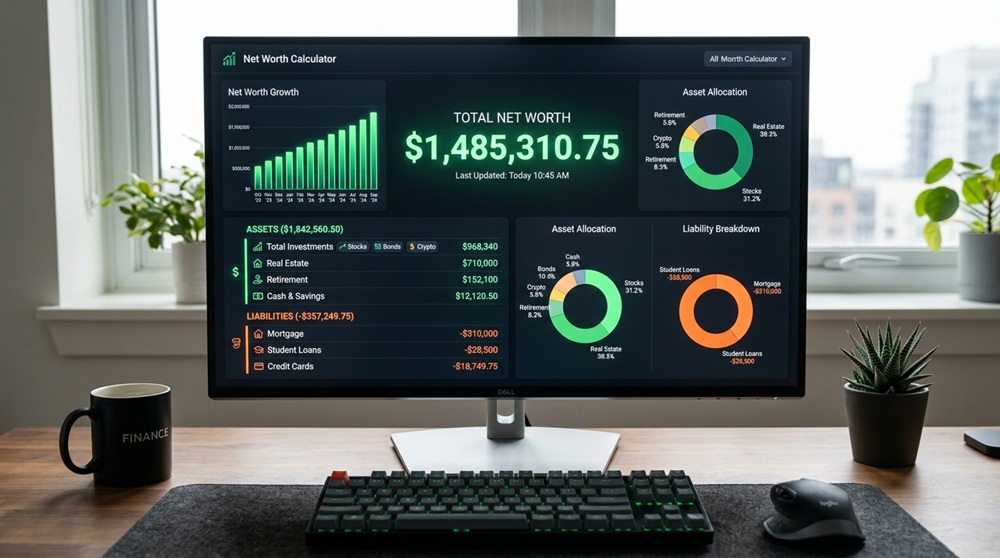
During the conversation, use a combined net worth calculator by entering both partners’ current assets and liabilities into one calculation. Seeing the combined total, debt ratio and asset categories in one view can make the discussion more practical and less emotional.
What to Do When the Numbers Are Very Different
Unequal starting positions are common. One person may have invested since their first job. Another may have completed graduate school and carries student debt. One may own property. Another may have supported family members or rebuilt after a previous financial setback.
The partner bringing more assets should not treat the conversation as an audit of character. The partner bringing more debt should not hide balances out of embarrassment.
Instead, ask three useful questions:
- Which debts are most expensive or urgent?
- Which assets need protection or continued contributions?
- How will future income be used to support shared goals?
For example, a couple may agree to eliminate high-interest credit card debt quickly while each person continues receiving any available retirement match through work. They may also agree that premarital savings remain individually held while future home savings are built jointly.
The goal is not perfect equality on the wedding date. It is a plan both partners understand and support.
The Prenup Question: Financial Planning, Not a Test of Love
A prenuptial agreement can be relevant when one partner enters marriage with significant assets, a business, expected inheritance, children from a previous relationship or substantial debts. It may also help couples document how premarital assets, future earnings or shared obligations will be handled.
A prenup is not automatically distrustful. It requires a deeper financial conversation before marriage, including disclosure of assets and liabilities.
The legal effect of a prenup depends on state law, timing, disclosure, fairness and how the agreement is prepared. Couples considering one should each obtain independent legal advice well before the wedding, rather than using a generic agreement at the last minute.
Even couples who do not need a prenup can benefit from the same process: list assets, list debts and agree on the principles that will guide financial decisions.
Joint vs. Separate Accounts: Choose a System You Can Run
Marriage does not require one banking structure. The right setup is the one that supports transparency, bill payment, personal autonomy and shared goals.
A fully joint system places income and expenses in shared accounts. It is simple to monitor, but it requires strong agreement about spending.
A separate-account system with a joint bills account lets each partner maintain personal banking while contributing a planned amount to household expenses.
A three-account system works similarly: each person keeps individual spending money, while a joint account pays rent or mortgage, utilities, groceries, insurance and shared savings goals.
Whatever structure you select, both partners should know where bills are paid, which debts are joint and how savings goals are tracked. The Consumer Financial Protection Bureau notes that joint credit card accounts affect both spouses’ credit scores, which makes shared borrowing decisions especially important.
Setting Shared Financial Goals
Once your starting net worth is visible, decide what you want the next version of the balance sheet to show.
Set a one-year goal first. That might be paying off $8,000 in credit card debt, building a $15,000 emergency fund or contributing a combined $12,000 to retirement accounts.
Then set three-year and ten-year goals around major life plans: buying a home, starting a family, building a business, reaching a retirement savings level or reducing the need for debt.
Couples interested in financial independence may also estimate a long-term target using annual household spending. Multiplying annual expenses by 25 is a useful starting framework for a portfolio-funded lifestyle, though it is not a guarantee and needs to account for taxes, healthcare and retirement timing.
Review combined net worth monthly or quarterly. The AICPA recommends regular financial check-ins for couples because goals, spending and circumstances change over time.
For additional guides on building assets, reducing liabilities and understanding financial progress, visit NetlyWorth.
The Best Financial Partnership Starts With Honest Numbers
Marriage does not require matching incomes, identical savings histories or a perfect balance sheet. It requires clarity. Calculate what you own, disclose what you owe and decide how you will build from the combined starting point. The first shared net worth number is not a score of the relationship. It is the foundation for making financial decisions as a team.